You’ve just paid off debt. Now what? If you’re wondering how to talk about financial goals without sounding like a bore at the dinner table, you’re not alone. Let’s be honest: debt can feel like a loud, messy roommate. Once it’s out of the house, you want your money goals to have their own cozy corner—and a plan that doesn’t scare people away.
Why talking about money goals after debt payoff actually helps
So you’ve crushed the debt, big deal, right? Not so fast. Naming goals aloud makes them real, not just vibes. When you articulate what you want next, you create accountability, spark motivation, and invite support from the people who care about you.
– You turn abstract dreams into concrete targets.
– You turn a personal win into a shared strategy with partners or friends.
– You invite feedback that helps you stay on track.
Ask yourself: what’s the first goal that gets you excited? Your future self will thank you for the clarity.
Start with a quick recap of your debt victory
Paint the picture in one sentence
Before diving into new goals, summarize your payoff story in a single, honest sentence. Example: “I paid off $20k in two years and I learned to say no to impulse buys.” This isn’t bragging; it’s anchoring your mindset.
Free workbook: Want a simple way to practice this? Get the free 7-Day Couples Communication Reset.
Get the Free 7-Day ResetHighlight the changes you made
– Automated payments? Check.
– Emergency fund tucked up to a healthy level? Check.
– No more monthly debt payments siphoning your happiness? Check.
Keep it short and celebratory. People love a win. And FYI, your future self loves it too.
What comes next: setting healthy financial goals
Choose goals that feel doable and exciting
After debt, you want momentum, not burnout. Pick 2–3 goals that genuinely excite you and align with your values.
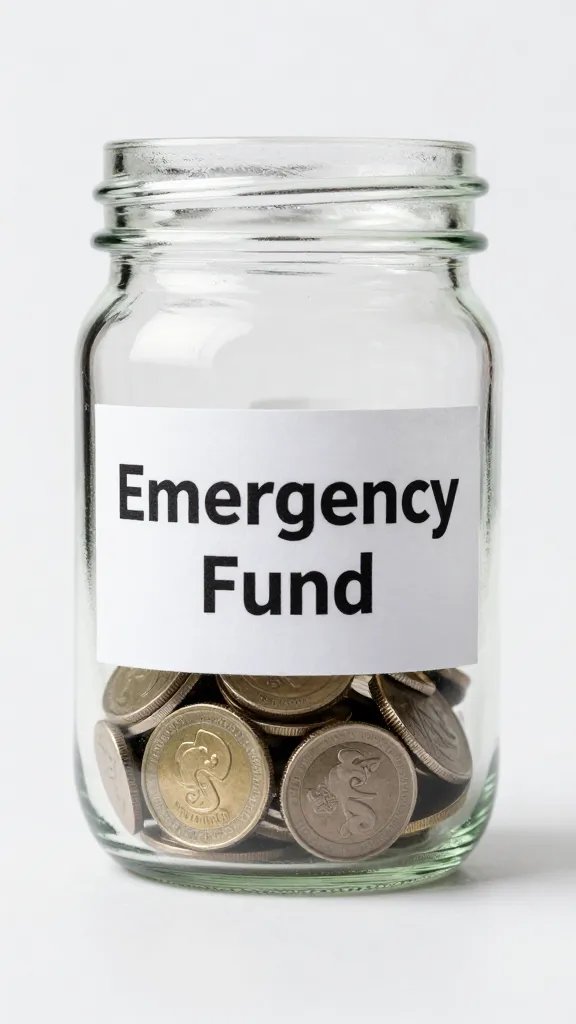
– Short-term: build a bigger emergency fund (3–6 months of expenses).
– Medium-term: save for a big purchase (car, travel, home improvements).
– Long-term: start or max out retirement contributions.
Ask yourself: would you be stoked to hit these in 6–12 months? If yes, you’re on the right track.
Make goals specific and measurable
Vague goals fade away. Get concrete.
– Instead of “save more,” aim for “save $500 per month into a high-yield account.”
– Instead of “invest more,” target “contribute $300 per month to retirement (IRA/401k).”
Specific numbers + deadlines keep you honest and focused.
Frame goals around behaviors, not just outcomes
Money results follow habits. Tie goals to daily or weekly actions.
– Automate transfers the day after payday.
– Track expenses in a simple app or notebook.
– Review your budget every Sunday, no excuses.
Behavioral targets are repeatable, not heroic.
Smart ways to talk about it with your partner or friends
Start with gratitude, not pressure
“Hey, I’m excited we paid off the debt together. I want to *keep* this energy going.” People respond better to appreciation than pressure.
Use clear language and avoid blame
If you’re in a partnership, use neutral wording: “I’d like us to set aside $X for emergencies.” Avoid phrases that imply blame for past spending.
Agree on a shared plan, with solo flexibility
Couples should have a joint plan, plus each person’s personal goals. For example, you might share an emergency fund target while you each pursue individual travel goals.
Practical steps to implement new goals
Create a simple budget that supports your targets
– List fixed expenses: rent, utilities, insurance.
– Identify variable spends you’re willing to reduce: dining out, subscriptions.
– Allocate money toward goals first, then the rest is “fun money.”
This is the “pay yourself first” mindset in action, and it’s ridiculously effective.
Need help putting this into practice? The free 7-Day Couples Communication Reset gives you simple daily prompts for calmer conversations.
Download the Free ResetAutomate, automate, automate
If you forget to save, automation saves you from yourself.
– Set automatic transfers to a checking or savings account.
– Auto-escalate contributions when you get raises.
– Schedule periodic reviews (quarterly or semi-annual) to adjust amounts.
No manual babysitting required.
Track progress without turning it into a soap opera
Keep it light. Use a simple dashboard or a calendar reminder.
– Monthly check-ins: “Are we on track for the emergency fund?”
– Quarterly celebrate wins, big or small.
– If you slip, diagnose, don’t doom-scroll. Adjust and move on.
Common pitfalls to dodge (and how to bounce back)
Overstretching your budget
New goals feel thrilling, but overcommitting leads to burnout. Start with a cushion—build a little safety net before chasing loftier dreams.
Undermining your goals with bad timing
Sync big goals with stable income cycles. Don’t launch a home remodel or a fancy vacation right after debt payoff unless you’ve got a solid plan.
Neglecting mental and emotional energy
Money talk isn’t purely math. It’s mood, willpower, and motivation. Keep conversations light, honest, and forgiving.
FAQ
Why should I talk about goals aloud after paying off debt?
Talking aloud helps crystallize intentions, invites support, and turns vague dreams into actionable plans. It also makes you accountable to someone besides yourself, which can be surprisingly motivating.
How many goals should I set right after payoff?
Aim for 2–3 core goals that cover emergency safety, a meaningful short-term objective, and a long-term contribution like retirement. You can expand later as you gain confidence.
What if my partner and I disagree on priorities?
Have a calm, goal-focused conversation. List each person’s top priorities, find overlaps, and compromise on a plan that respects both perspectives. If needed, bring in a financial coach for a neutral check.
How often should I review and adjust goals?
Quarterly reviews work well for most people. If life throws a curveball (job change, relocation), adjust sooner. The key is staying honest with yourself.
Is it okay to treat some goals as “fun money”?
Absolutely. Budgeting isn’t about rigidity; it’s about freedom with boundaries. Allocate a small, clearly defined amount for fun to keep motivation high without derailing progress.
Conclusion
You’ve paid off debt. That victory isn’t a finish line; it’s a launching pad. Now you get to decide what your money stands for in the next chapter: security, dreams, and a little less stress. Talk about your goals like you’d chat with a friend who’s rooting for you. Be specific, keep it simple, and celebrate every milestone—no matter how small.
If you’re feeling bold, map out your first 60 days of action today. Automate a couple of transfers, set a mini-check-in date, and share your plan with someone you trust. IMO, the most powerful thing you can do after debt payoff is keep the momentum going—one purposeful step at a time. FYI, you’ve got this.
Ready to practice better communication?
Start with the free 7-Day Couples Communication Reset, or explore the full Couples Communication Workbook & Handbook for deeper guided exercises.